See also


 02.10.2026 09:46 AM
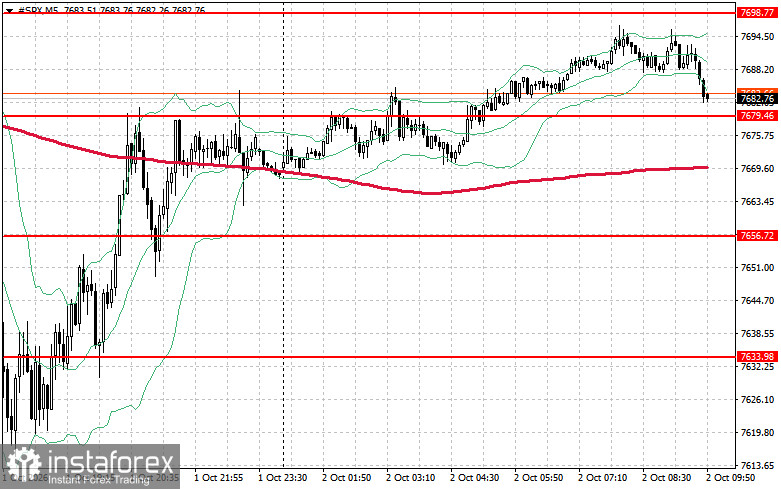
US equity indices finished broadly unchanged yesterday despite the bond market pricing a series of additional Fed hikes. The S&P 500 gained 14.91 points to 7,666.45 (+0.19%). The Nasdaq Composite added 10.54 points to 26,871.60 (+0.04%). The Dow Jones Industrial Average rose by 20.51 points to 50,926.56 (+0.04%). That muted equity reaction in the face of rising yields suggests that investors do not yet view further Fed tightening as an immediate threat to corporate profits, at least until Friday's payrolls report.
Bond traders, however, are making such large bets on more Fed hikes that a single softer jobs print is unlikely to materially change the picture. The US Labor Department will publish September payrolls on Friday. The economist consensus calls for roughly +90k jobs vs. +162k in August. On paper, the slowdown looks meaningful, but in the context of this year's monthly averages, it still points to a resilient labor market. Moreover, that leaves the Fed room to continue tightening to fight inflation that has remained above target for five consecutive years.
On Thursday, the Treasury sell-off temporarily eased but for reasons largely unrelated to improving US growth prospects. Rising concerns about Europe's ballooning fiscal burden pushed investors toward Treasuries, and Fed officials Michelle Bowman and Philip Jefferson urged caution, suggesting that policymakers may want to wait before deciding on further interest rate hikes.
That dynamic pushed the two-year yield roughly 10 basis points lower to just under 4.8%, and the 10-year retreated somewhat from a 24-year high. However, the fundamentals that drove yields higher last week are still in place: oil hovers near $100/bbl, and there is little sign of progress toward ending the Iran conflict, keeping an inflation premium in the market. Large federal deficits and an AI investment boom continue to underpin economic demand, and headline inflation has already jumped above 3% this year. It is the combination of these forces, not payrolls alone, that is shaping the Treasury yield path today.
Recall that earlier this week, futures traders pared back some of their upside bets on rate hikes and do not expect further moves before the December meeting. Still, the market continues to price in at least three 25?bp hikes by July. That means that even after Thursday's pullback, investors remain far from betting on an imminent Fed pause. Any surprise in Friday's payrolls, either way, will be the week's defining event for rate expectations.
In my view, equities' subdued reaction to record-high yields will not persist if Friday's jobs data confirms labor market strength. That outcome would strengthen arguments for additional tightening and push yields back up early next week. I would not rule out the 10-year Treasury testing a new multi-year high on a strong payrolls print, while stocks, judging by today's muted moves, would likely hold near current levels until a clear real threat to corporate profits emerges.